Key Takeaways
Surveys and Foundation Endorsements play an important role in construction
finance and protect financial institution’s physical interests in real estate.
It’s important for construction lenders to fully understand their purpose and
benefits when utilizing the tools.
Surveys and Foundation Endorsements play an important role in construction
finance and protect the financial institution’s physical interests in real
estate. It’s important for lenders to fully understand their purpose and
benefits when utilizing the tools.
The construction loan agreement is one of the most important legal instruments
in construction finance and while these agreements tend to have small variations
from the various document providers, they all tend to have similar covenants to
cover the physical, financial and legal risk that can be associated with
construction finance. Requiring the borrower to provide surveys during the
construction process is essential in verifying that the home is being
constructed in the correct location and does not encroach on any easements,
setbacks, other properties, or violate the rights given to other parties.
Because, at the end of the day, nobody wants to move a new structure, or even
worse tear it down and start over again.
At their core, surveys are used to establish the property’s location, boundary
lines and other issues that can be identified within a property. Lenders can
leverage surveys to protect their physical interest by requiring the borrower,
by means of their construction loan agreement, to demonstrate that the structure
is meeting the covenants of the agreement. More specifically, to demonstrate
that the structure is being constructed in the correct location and does not
pose risk to the collateral.
An additional option to protecting a lender’s risk is to obtain a foundation
endorsement from the title company. This is more common in states like
California where surveys are near cost-prohibitive. The foundation endorsement
is a cost-effective way to protect the lender’s interest. With a foundation
endorsement, the title company will review the location of the forms or
foundation to determine if there are any issues and issue an endorsement to the
title policy that ensure the lender against loss due to the structure’s
location. Some title companies may require that the borrower provide a survey to
issue the endorsement.
What is involved With a Survey?
A survey focuses simply on the foundation and possibly the elevation of a
structure if it is in a flood zone, providing an effective “snapshot” of the
foundation as of a certain date. A surveyor will visit a property to document
this critical stage of construction. The survey will plot the location and
dimensions relative to property lines, and/or in comparison with previous site
plans or plats. Elevation readings may also be taken throughout the foundation
to identify any high or low points, serving as a baseline measurement. The
results are documented in a report that is certified by the surveyor. It’s
important to require that the borrower, builder, lender and title company are
intended users of the survey.
How to Obtain a Foundation Endorsement
Foundation endorsements are issued by the title company that provided the
original title policy. The process starts by contacting the title company and
inquiring about what they require to issue the ALTA 102.5 Foundation
Endorsement. The form is standardized, however the title company requirements
may vary. At the end of the day, it’s up to the underwriter to make the
determination of what they require to issue the endorsement.
Once requested, the title company will be responsible for confirming the
location of the foundation. They may do this by obtaining their own inspection,
sending an employee of the title company to the property, asking the requesting
party for the last progress inspection, or requesting a survey from the
borrower, owner or builder.
Considerations:
- Foundation Endorsements are more common to requests in California and are
generally preferred due to high costs of surveys in the state. Surveys in
California tend to be significantly higher in cost in comparison to a
foundation endorsement.
- Some title companies may issue the endorsement without a survey while others
may require that the builder obtain a survey so they may review it. If you
offer the title company a copy of the last progress inspection that shows the
foundation location, it’s a possibility that they may not accept it, but if
they do accept it then it allows for a faster and less expensive solution.
- As a best practice, it is recommended that this research be done proactively
vs reactively; meaning, you should provide the steps necessary to the borrower
and builder before they close the loan with a friendly reminder of this
obligation before they pour the foundation.
When to Obtain a Foundation Endorsement
Foundation Endorsements should be obtained as early as possible. They may be
obtained as early as having the forms set for the foundation, prior to the pour.
Having an endorsement at this stage is strategic since any issues can be
identified and changes made before the builder commits to pouring a foundation.
If issues are found after the foundation is poured, it could be problematic
since the foundation may need to be altered or removed entirely. You wouldn’t
want to have the home framed and find out that it all needs to be demolished and
rebuilt because of an easement issue. Although it is recommended as a best
practice that the survey be obtained before the first draw, some builders may
simply forget. Do your best to be proactive.
How To Read A Foundation Endorsement
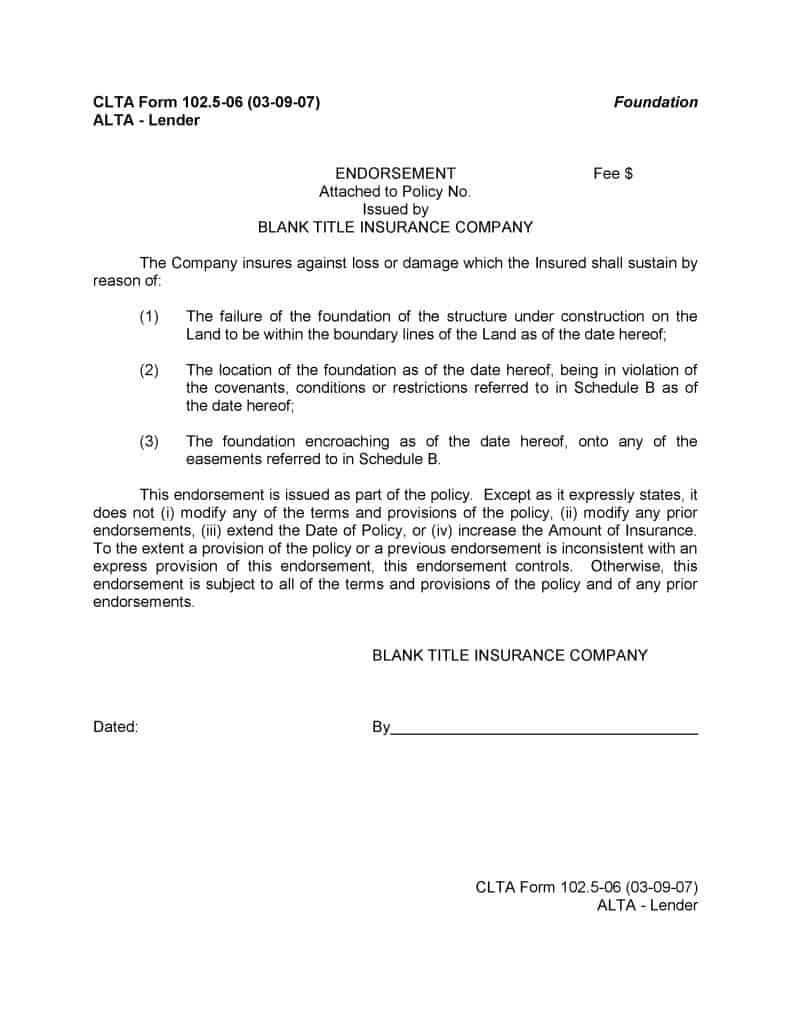
There is a copy of the 102.5 Foundation Endorsement as an example to review.
Note the three reasons that the title company is insuring and look for any
exemptions that the title company has added. These exemptions are how the title
company will notify you of risk and where they will not provide insurance
coverage. Sometimes exemptions are found that identify known issues. If you find
issues contact the borrower and builder to discuss as soon as possible.
Survey and Foundation Endorsement FAQs
How much do endorsements and surveys cost?
The cost of the foundation endorsement varies from state to state but will be
the same cost for any lender. In other words, you don’t need to shop around. The
endorsements don’t cost a lot of extra money but if a survey is required to
issue this endorsement the cost may be more significant. A foundation
endorsement should cost similar to a mechanics lien endorsement while a survey
should cost between $250-$700 with the national average at $422 per
HomeGuide.com.
Do I collect surveys or foundation endorsements on renovation projects?
Renovation projects typically would not require surveys or foundation
endorsements unless the home is adding new square footage in the form of a ‘new
addition’.
How do I know which one to collect?
Most states it will be customary to simply obtain and review the survey without
needing an endorsement from the title company. In some states like California, a
survey is cost-prohibitive and the title company will issue an endorsement and
provide any instructions and what will be involved. It’s recommended that the
lender obtain a foundation endorsement to have the greatest level of protection.
Who pays for the surveys or foundation endorsement?
The obligation to provide the survey is the responsibility of the borrower,
however, the builder could also include this expense in their construction costs
if it is agreed to between the parties.
Does the borrower work with Title to request foundation endorsements?
No, foundation endorsements typically require the lender to work with title to
facilitate the request since the endorsement is to the lender’s title policy,
while the borrower would be obligated to provide a survey to support the
request.
Learn more about how Land Gorilla solutions help to make construction financing
faster, safer, and more efficient, here.